MEDICARE BASICS FOR PATIENTS AND FAMILIES
Medicare Explained: Parts A, B, C, and D
Understanding Medicare can feel complicated, especially when you're comparing coverage options for yourself or a family member. Medicare has four main parts, each serving a different purpose.
This guide explains what Medicare Parts A, B, C, and D cover, how Original Medicare differs from Medicare Advantage, and where to find reliable information to help you understand your options.
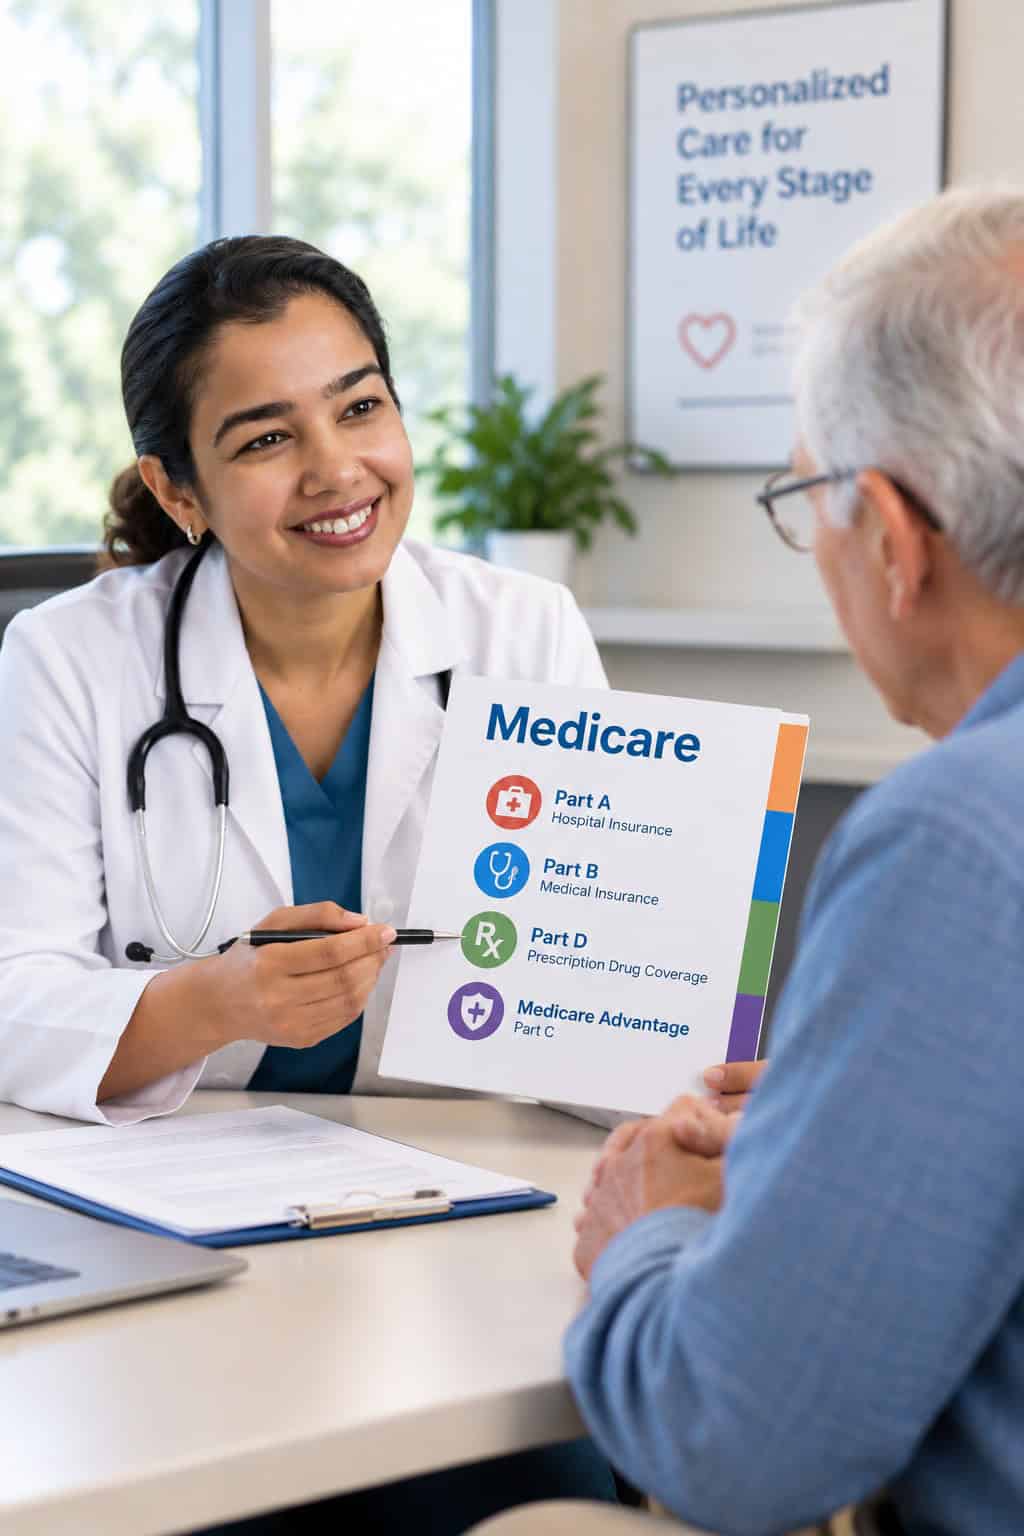
Table of Contents
What Is Medicare?
Medicare is a federal health insurance program primarily for people age 65 and older. Certain younger people may also qualify because of a disability, end-stage renal disease, or amyotrophic lateral sclerosis (ALS).
Medicare helps pay for eligible healthcare services, but it does not cover every medical expense or most long-term custodial care. Understanding the parts of Medicare can help you recognize the differences between hospital coverage, outpatient medical services, prescription drug coverage, and private Medicare health plans.
The four main parts are:
- Part A: Hospital insurance.
- Part B: Medical insurance.
- Part C: Medicare Advantage plans.
- Part D: Prescription drug coverage.
Your coverage, premiums, deductibles, copayments, and provider choices depend on the Medicare options and plans you have. Review the details of your own coverage before making healthcare or enrollment decisions.
What Does Medicare Part A Cover?
Medicare Part A is hospital insurance. For eligible beneficiaries, it helps cover certain inpatient hospital services, skilled nursing facility care under qualifying conditions, hospice care, and some home health services.
Part A does not pay for every service or every day of care. Coverage depends on Medicare's rules, medical necessity, eligibility requirements, and other conditions.
Many people qualify for premium-free Part A based on their own or a spouse's Medicare-covered work history. Others may need to pay a premium.
Before receiving care, ask the healthcare facility whether the service is covered and whether you may have deductibles or other out-of-pocket costs.
What Does Medicare Part B Cover?
Medicare Part B is medical insurance. It helps cover eligible services from doctors and other healthcare professionals, outpatient care, certain home health services, durable medical equipment, and many preventive services.
Examples of services that may be covered include eligible physician visits, certain screenings, vaccines, and annual wellness visits. Coverage depends on the service, applicable Medicare rules, and whether the requirements are met.
Most people pay a monthly premium for Part B, and deductibles or coinsurance may also apply. Some people qualify for programs that help with Medicare costs.
If you're choosing a doctor or scheduling an appointment, confirm that the provider accepts your specific coverage and ask whether any referral, authorization, or out-of-pocket payment may apply.
What Is Medicare Part C (Medicare Advantage)?
Medicare Part C is also known as Medicare Advantage. These plans are offered by Medicare-approved private insurance companies and provide an alternative way to receive Medicare-covered Part A and Part B benefits.
Many Medicare Advantage plans also include prescription drug coverage. Some offer additional benefits, such as certain vision, hearing, or dental services, depending on the plan.
Medicare Advantage plans can have different premiums, copayments, provider networks, and rules for accessing services. Some require referrals or prior authorization for certain care. Your costs and choices depend on the specific plan.
Before enrolling, check that your preferred doctors, hospitals, medications, and other important services are covered under the plan's current terms.
What Does Medicare Part D Cover?
Medicare Part D helps cover outpatient prescription medications through Medicare-approved drug plans. You can generally obtain Part D coverage through a separate prescription drug plan with Original Medicare or through a Medicare Advantage plan that includes drug coverage.
Each plan has its own list of covered medications, known as a formulary, as well as its own premiums, cost-sharing rules, and pharmacy arrangements.
Before choosing a drug plan, check your current prescriptions, dosage requirements, preferred pharmacies, and the plan's coverage rules. A plan that works well for one person may not be the best option for someone taking different medications.
Review your drug coverage whenever you have an opportunity to change plans, particularly if your medications or healthcare needs change.
What Is the Difference Between Original Medicare and Medicare Advantage?
The two main ways to receive Medicare coverage are Original Medicare and Medicare Advantage. Understanding their differences can help you identify which details to investigate when comparing options.
Original Medicare
Original Medicare includes Part A and Part B. You can generally use any doctor or hospital in the United States that accepts Medicare, subject to Medicare's coverage rules. You can add a separate Part D prescription drug plan and may be able to purchase Medicare Supplement Insurance (Medigap) to help pay certain out-of-pocket costs.
Original Medicare does not have an annual out-of-pocket maximum for covered Part A and Part B services unless you have additional coverage that provides one.
Medicare Advantage
Medicare Advantage plans are offered by Medicare-approved private insurers. They cover Medicare Part A and Part B benefits and often include Part D drug coverage. Plans may offer additional benefits but can have provider networks, service-area restrictions, and different cost-sharing rules.
Which option is right for you?
The answer depends on your healthcare needs, preferred doctors, prescription medications, budget, travel habits, and the specific plans available to you. Compare the plan documents carefully rather than choosing based on the monthly premium or advertised extras alone.
What Is Medicare Supplement Insurance (Medigap)?
Medicare Supplement Insurance, often called Medigap, is private insurance that can help pay certain out-of-pocket costs associated with Original Medicare, such as eligible deductibles, copayments, and coinsurance.
Medigap is different from Medicare Advantage. It supplements Original Medicare rather than replacing it, and it generally cannot be used to pay Medicare Advantage plan cost-sharing.
Medigap policies are standardized by plan type in most states, although premiums, availability, and certain details can vary. Medigap policies generally do not cover long-term custodial care, routine vision or dental care, or most hearing aids.
Before changing coverage, understand how your current insurance works, whether you can obtain the new coverage you want, and whether you might lose rights or benefits by making a change.
How to Compare Medicare Coverage Options
When comparing Medicare coverage, look beyond the monthly premium. Consider how each option fits your current and anticipated healthcare needs.
Use this checklist when reviewing your choices:
- Doctors and hospitals: Are your preferred providers included or do they accept the coverage?
- Prescription medications: Are your current medications covered, and what will they cost?
- Total costs: Compare premiums, deductibles, copayments, coinsurance, and potential out-of-pocket expenses.
- Access to care: Check whether referrals, prior authorization, or network restrictions apply.
- Additional benefits: If dental, vision, hearing, or other benefits matter to you, verify exactly what each plan includes.
- Future changes: Understand when you can change plans and how switching could affect your coverage.
For official Medicare plan comparisons, use Medicare.gov or speak with your State Health Insurance Assistance Program (SHIP), which offers free, personalized Medicare counseling.
Village Physicians can discuss your medical care and help you understand questions to raise about your coverage. For insurance enrollment decisions, consult Medicare or a qualified Medicare counseling resource.
Additional Medicare Resources
Here are three authoritative links to include in the Village Physicians Medicare article. All are official U.S. government resources.
- Medicare.gov — Parts of Medicare — Explains Parts A, B, C, and D, Original Medicare, Medicare Advantage, and Medigap.
- Medicare.gov — Medicare Basics — Covers how Medicare works, general costs, enrollment, and coverage options.
- CMS — Medicare Supplement Insurance (Medigap) — Explains how supplemental insurance works with Original Medicare and helps cover certain out-of-pocket costs.
Frequently Asked Questions About Medicare
Medicare can be confusing, especially when comparing Original Medicare, Medicare Advantage, prescription drug coverage, and supplemental insurance. These frequently asked questions explain the key differences, what each part of Medicare covers, and where to find reliable information to help you make informed decisions about your healthcare coverage.
What are the four parts of Medicare?
Part A helps cover inpatient hospital care and certain related services. Part B helps cover doctors' services, outpatient care, and many preventive services. Part C, also called Medicare Advantage, provides an alternative way to receive Medicare Part A and Part B benefits through a private plan. Part D helps cover prescription drugs.
Is Medicare Part A free?
Many people qualify for premium-free Part A based on their own or a spouse's work history. Others may need to pay a premium. Even when there is no monthly premium, deductibles or other cost-sharing may apply.
Do I need both Medicare Part A and Part B?
Many people enroll in both Part A and Part B, but individual circumstances differ. Your eligibility, employment or other health coverage, and enrollment timing can affect your decision. Review your situation with Social Security or Medicare before delaying or declining coverage.
Does Medicare cover prescription drugs?
Medicare Part D provides outpatient prescription drug coverage through approved drug plans. Many Medicare Advantage plans include drug coverage, while people with Original Medicare can generally enroll in a separate Part D plan.
What is the difference between Medicare Advantage and Medigap?
Medicare Advantage is an alternative way to receive Medicare Part A and Part B benefits through a private plan. Medigap is supplemental insurance that helps pay certain out-of-pocket costs under Original Medicare. They serve different purposes, and Medigap generally does not work with Medicare Advantage.
Can I change my Medicare plan?
You may be able to change coverage during certain enrollment periods or if you qualify for a special enrollment opportunity. The rules depend on your circumstances and the type of coverage you have. Check Medicare.gov before making changes.
Does Medicare cover every medical expense?
No. Coverage depends on the service, medical necessity, eligibility rules, and the type of Medicare coverage you have. You may still have premiums, deductibles, copayments, coinsurance, or expenses for services Medicare does not cover.
Where can I get free help understanding Medicare?
Medicare.gov and 1-800-MEDICARE provide official Medicare information. Your State Health Insurance Assistance Program (SHIP) also offers free, personalized counseling to help people understand coverage options and enrollment.
About the Physician
Nasiya Ahmed, MD
Dr. Nasiya Ahmed is a physician at Village Physicians in Houston, Texas, with a practice focused on Internal Medicine, Geriatrics, Hospice, and Palliative Medicine. She provides care for adults with a range of medical needs and helps patients make informed decisions about their health.
If you have questions about your medical care or how to coordinate healthcare services with your coverage, discuss your individual needs with your healthcare provider.
Have Questions About Your Healthcare Needs?
Understanding your Medicare coverage is an important part of planning for healthcare, but choosing coverage and receiving medical care are separate decisions.
Village Physicians provides adult healthcare in Houston, including care for older adults. If you would like to discuss your medical needs or ask about arranging an appointment, contact our office.
For questions about Medicare eligibility, plan benefits, enrollment, or insurance comparisons, consult Medicare.gov or a State Health Insurance Assistance Program.
Questions? Call our office at (832) 930-7877.